
In brief
- EUR 2 per item, not per parcel. The European Commission has set the Union handling fee at 2 euro, due when goods sold in distance sales to a customer in the Union are released for free circulation, that is, cleared on entry.
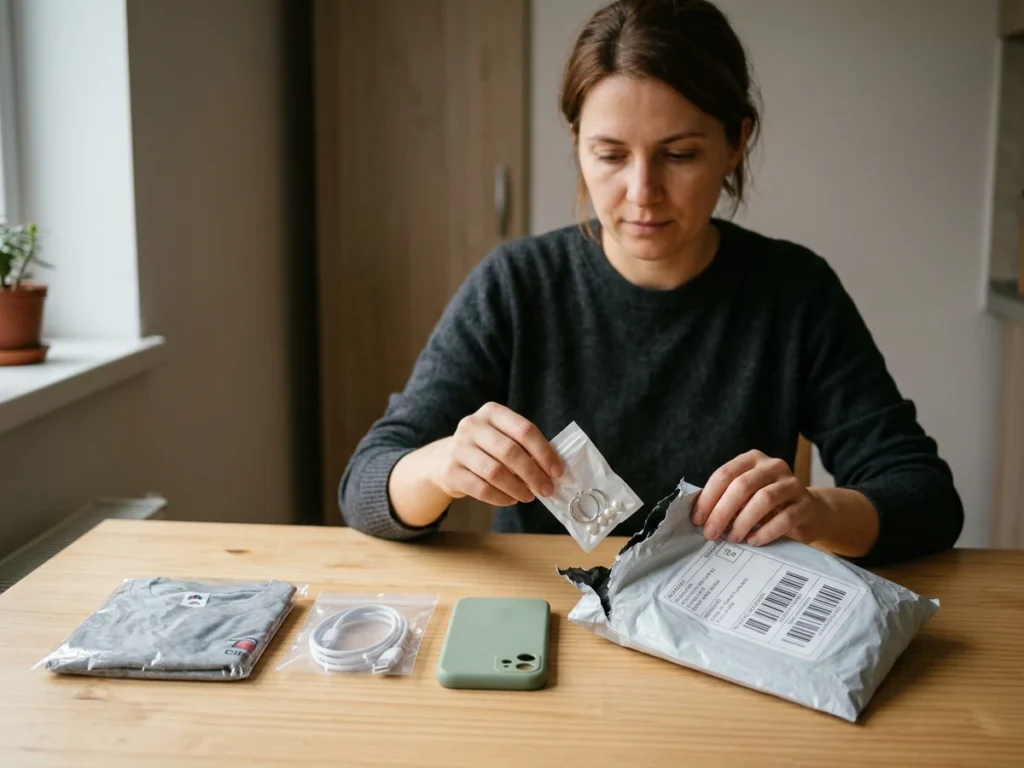
- One parcel can hold several items. In the language of the new Union Customs Code, an „item” is a group of goods from the same consignment sharing the same tariff classification, the same description and the same origin. Three identical T-shirts in one envelope are one item and cost 2 euro; a T-shirt, a charging cable and a phone case in the same envelope are three items and cost 6 euro.
- The buyer does not hand the money over at customs. The fee is owed by the debtor of the customs debt on import and, where there is no customs debt at all, by the person who would have been the debtor, namely the importer for distance sales or the platform facilitating the sale. Payment is made to the customs authorities at least once a month.
- It applies from 1 November 2026. The regulation entered into force on the date of publication, 22 October 2026, but Article 2 defers application by ten days. The fee is non-refundable, so it does not come back even if the goods are returned.
Published: Official Journal of the European Union, L series, 2026/2152 of 22 October 2026
In force from: 22 October 2026, the date of publication, under the first paragraph of Article 2; it applies from 1 November 2026, under the second paragraph of Article 2
Parcels ordered from outside the European Union become 2 euro dearer for every item inside them, from 1 November 2026. The amount was set by Commission Delegated Regulation (EU) 2026/2152, published in the Official Journal of the European Union, L series, 2026/2152 of 22 October 2026. The instrument resembles nothing that existed until now at the point where goods enter the Union: it is not a customs duty, which is calculated as a percentage of the value of the goods and applied product by product, as happens with the anti-dumping duties on glass beads from China, and it is not value added tax either. It is payment for an administrative service, the flat sum the customs authority charges for having verified the data of a consignment, put it through risk analysis and decided whether it comes in or not.
The text of the regulation itself has a single substantive article and a single figure in it. Article 1 states that „the amount of the Union handling fee laid down in Article 20(2) of Regulation (EU) 2026/2108 shall be EUR 2 per item”. Everything else in the act, the four recitals of the preamble, explains why 2 and not something else, while Article 2 fixes the dates. To understand what the 2 euro buys and who takes it out of their pocket, the act has to be read together with Regulation (EU) 2026/2108 of the European Parliament and of the Council of 16 September 2026, the new Union Customs Code, which replaced the 2013 Code and set up the European Union Customs Authority.
It is there, in Article 20, that the answers missing from the 2 euro regulation are found. Paragraph 1 lays down the general rule: customs authorities may not charge for customs controls or for any other application of the customs legislation carried out during the official opening hours of their competent customs offices. Paragraph 2 is the derogation, and the only one: by way of derogation from that gratuity, customs collects a fixed fee per item for handling a request for release for free circulation, but only where the goods were sold in distance sales. Cross-border e-commerce is therefore the only type of import that pays for clearance by the piece.
On 29 October the reduction of the comprehensive guarantee for parcels under EUR 150 entered into force: firms with AEO status post 30 %, and the rule applies from 1 November 2026.
Also from 1 November 2026, every product in a parcel must be declared at customs with the merchant’s code and the manufacturer’s code, including on the H7 declaration.
From 6 November 2026 the procedure also changed for operators working in transit: authorised consignor and consignee status is granted only with at least 50 transit operations a year, per customs office.
What it changes in practice
The first effect, and the one felt directly in the price, is the unit of calculation. The fee applies to each item, and „item” is defined in Article 5(78) of the Union Customs Code as „one or more goods in a consignment sharing the same tariff classification, description and, where provided for as part of the data requirements applicable to the relevant customs declaration or to the data to be provided or made available to the customs authorities, origin”. The practical consequence is easy to check on any shopping basket: an envelope with five identical pairs of socks is one item and costs 2 euro, while an envelope with five different small objects is five items and costs 10 euro. The sum is decided by the number of distinct positions declared in the consignment, and weight, volume and the number of packages stay outside the calculation.
The second effect is that the fee is owed even where the goods pay no customs duty at all. Under Article 20(5) of the Union Customs Code, the handling fee is paid by the debtor of the customs debt on import, at the moment that debt is paid, and if there is no customs debt, by „the person that would have been the debtor in the event of a customs debt”. In other words, an object that comes in at zero customs duty still comes in at 2 euro per item. For the matters Article 20 does not regulate, the same paragraph refers to the rules on customs debt, applied „mutatis mutandis”, meaning the ordinary mechanisms of determination, guarantee and recovery.
The third effect concerns those who actually carry the money to customs. The buyer in Romania fills in nothing and pays nothing at the counter. The payer is the economic operator: the importer for distance sales, which in the definition in Article 5 of the Code is „either the person supplying goods in distance sales or the person facilitating distance sales”, that is, the e-commerce platform too. The money goes to the competent customs authorities at least once a month, not with every consignment, which means that firms clearing large volumes will have to keep monthly records by item, not by parcel. The cost reaches the buyer through the price, the delivery charge or the platform’s commission, not through a separate receipt.
The fourth effect is the most unwelcome and the least visible: Article 20(6) of the Code provides that the Union handling fee is non-refundable. Returning the product, withdrawing from the contract within the legal period or refusing the parcel does not bring the 2 euro back, because the service they paid for, data verification and risk analysis, has already been performed.
The fifth effect is territorial and reaches people who might have thought themselves outside the game. Recital (1) of the regulation states that the fee applies to customers in the customs territory of the Union as defined in Article 3 of the Union Customs Code, where Romanian territory is listed explicitly, and that it also covers customers in those parts of the customs territory where Directive 2006/112/EC, on the common system of value added tax, and Directive (EU) 2020/262, on the general arrangements for excise duty, do not apply. These areas, which the act calls special fiscal territories, do not escape the handling fee, even though they escape VAT and excise duty.
What has changed compared with the previous situation
Until 1 November 2026, clearing a parcel ordered from a country outside the Union had no price of its own. The 2013 Union Customs Code, Regulation (EU) No 952/2013, which Regulation (EU) 2026/2108 repeals, knew nothing of a Union handling fee. The buyer could pay customs duty, if the value exceeded the applicable thresholds, could pay import VAT and could pay the clearance commission of the courier or the customs agent, but that commission was a commercial price negotiated between firms, not a public charge. From 1 November 2026 a third layer appears, this one public, flat and identical in every Member State.
The logic of the charge has changed too. Customs duty and import VAT are calculated from the value of the goods, so they rise with the price of the product. The handling fee is calculated from the administrative cost of the check, so it does not look at the price at all. The result is regressive by construction: on an item worth 3 euro, the 2 euro is roughly 67% of the price; on an item worth 20 euro it is 10%; and on an item worth 100 euro it drops below 2%. Cheap goods split across many distinct positions pay the most, proportionally, and that is precisely the kind of goods the Asian platforms sell in the Union.
What has changed, thirdly, is the order in which the European customs reform comes into operation. The Union Customs Code applies, as a general rule, only from 21 September 2027, under Article 287(2). Article 20, which contains the handling fee, is taken out of that rule by Article 287(3)(b), yet paragraphs 1, 2 and 4 are themselves excluded from the early start there. For paragraph 2, the basis for collection, Article 287(4) provides a solution of its own: it applies ten days after the entry into force of the delegated act adopted pursuant to Article 20(10). That delegated act is precisely Delegated Regulation (EU) 2026/2152, so publishing it started the clock. The part of the reform that produces revenue begins 324 days ahead of the rest of the Customs Code.
What has not changed is everything the reader might expect to find here: the regulation does not touch the relief thresholds for low-value consignments, does not alter any import VAT rate and says nothing about the order in which the three obligations are calculated relative to one another. Anyone looking in this act for an answer to whether the customs duty relief threshold stays or goes will not find it, and the act does not even point to where that answer would be.
Advantages and disadvantages
What it improves
- A single figure, public and identical across the Union. A seller outside the Union can no longer arbitrage between Member States on the cost of clearance, because the 2 euro per item is the same in Romania as in the Netherlands.
- Payment does not fall on the consumer at the counter. Article 20(5) of the Union Customs Code makes the debtor the person who has or would have had the customs debt, that is, the economic operator, and payment is monthly rather than parcel by parcel.
- Charging per item rather than per parcel closes an avenue for avoidance. If the fee applied to the consignment, any seller would bundle ten objects into one envelope and pay once. Per item, bundling no longer helps.
- The costs taken into account are delimited in writing. Recital (3) expressly excludes from the calculation Member States’ investment in control infrastructure financed solely from national budgets, as well as the costs of market surveillance authorities not acting as a designated authority under Article 25 of Regulation (EU) 2019/1020, so the fee cannot be inflated with any related expense.
- The level is reviewed periodically rather than frozen. Under Article 20(8) of the Code, the Commission is required to produce a cost assessment report every two years, and recital (2) makes that report the condition for adjusting the amount.
- One substantive article, no annexes and no tables. The regulation leaves no room for interpretation on the figure itself: 2 euro per item, with no brackets, no coefficients and no exceptions to be applied at the counter.
What remains a problem
- The cost that the 2 euro is supposed to approximate is published nowhere in the act. Recital (3) speaks of „conservative assumptions”, of an assessment considered „moderate” and of „a reasonable and as realistic as possible projection” of the volume, but gives no unit cost figure and no number of consignments. The only figure in the regulation is the result, not the calculation.
- The effect is regressive and hits the cheap basket hardest. A basket of five different small objects at 4 euro each costs 20 euro in goods and 10 euro in fees, a 50% mark-up, while a single 200 euro object bears 1%.
- The fee is not refunded even on return. Non-refundability is written into Article 20(6) of the Code, so the right of withdrawal from distance contracts is left with a residual cost the buyer cannot recover from anyone.
- The collection procedure does not exist yet. An implementing act laying down the procedure for collecting the fee from the economic operator remains, under Article 20(11) of the Code, at the discretion of the European Commission: the wording used there is „may adopt”. The 2 euro regulation contains no procedural provision, so on 1 November 2026 declaration and payment run on the general mechanisms of customs debt.
- The Union’s calculation tool arrives more than a year and a half after the obligation. Under Article 20(7) of the Code, the Commission has until 30 June 2028 to provide „an appropriate IT solution at Union level for the purpose of the calculation of the Union handling fee”. Between 1 November 2026 and that date lie 607 days in which every operator does the calculation alone.
- Conversion into lei is not regulated in the act. The amount is set in euro, and the regulation does not say at what rate it is paid in a Member State that does not use the euro, nor on what date the rate is taken.
- The reduced amount promised by the Code is missing for now. For goods dispatched from a customs warehouse for distance sales, Article 20(4) of the Union Customs Code provides for a lower amount. The delegated regulation sets a single figure, and paragraph 4 becomes applicable only from 1 July 2028, under Article 287(5)(a), together with Article 145, which governs that type of warehouse.
Practical advice
- Count the distinct positions, not the parcels, before you order. If you need five different objects from a platform outside the Union, the administrative cost of the order is 10 euro, whether the seller sends them in one envelope or in five. If you need five units of the same object, with the same description and the same origin, the cost is 2 euro.
- Compare the final price, not the displayed price, with the one in shops inside the Union. On objects worth a few euro, a 2 euro difference per item can wipe out the advantage of importing directly. The threshold at which the fee becomes negligible, under 2% of the price, starts around 100 euro per item.
- Ask the courier firm or the customs agent for a breakdown by item. The fee is public and fixed; the firm’s clearance commission is not. The two sums are not of the same nature and should not end up on a single invoice line.
- Work out the loss on returns from the start. The handling fee is not refunded, so on a cheap object the return can cost more than the object is worth.
- Firms clearing e-commerce volumes should move their records from parcels to items by 1 November 2026. Payment is made at least once a month, and the basis of calculation is the declared position, with its own tariff classification, description and origin. Records kept by consignment will not produce the right amount.
- Online shops in Romania competing with direct imports can now recalculate the price gap. For a basket with several small products, their price disadvantage against a platform outside the Union narrows by 2 euro for every position in the competitor’s basket.
Frequently asked questions
Do I pay 2 euro per parcel or per thing inside it?
Does the fee come on top of customs duty and VAT, or replace them?
Does the relief threshold for low-value consignments disappear?
Do I get the money back if I return the product?
Do I have to do anything at customs for my parcel?
Why is the act dated 21 September 2026 if the fee starts on 1 November?
Why is there a handling fee only for online trade?
Errors and inconsistencies in the published text
- The second paragraph of Article 2 and recital (4), read against Article 287(4) of Regulation (EU) 2026/2108: 1 November 2026 may or may not fall within the time limit. The higher rule says that Article 20(2) „shall apply from 10 days after the entry into force of the delegated act”, while recital (4) of the present regulation describes its own solution differently, as application „the 10th day after the entry into force”, even though it claims to align the two. The difference is not stylistic. Article 22(2) of the Union Customs Code refers, for periods, dates and time limits, to Regulation (EEC, Euratom) No 1182/71, whose Article 3(1) excludes the day of the event from the calculation, whose Article 3(2)(b) makes a time limit in days end on the expiry of the last hour of the last day, and whose second subparagraph of Article 4(2) extends those rules to application fixed at a given number of days after an event. Applied to the entry into force of 22 October 2026, the ten days run from 23 October and end at the close of 1 November, so application „after ten days” begins on 2 November, not on 1 November. For declarations for release for free circulation lodged on 1 November 2026, two customs authorities acting in good faith can reach opposite conclusions on whether the obligation to pay exists, and the issuer can close the matter with a single corrigendum.
Editorial analysis
The regulation has four recitals and one substantive article, and its substance is a figure: 2 euro. The figure itself is not the problem; the problem is that nothing in the act allows it to be verified. Recital (2) explains, on the basis of Article 20(3) of the Union Customs Code, why the level of the fee has to correspond to the approximate costs of data verification, risk analysis, controls and relevant infrastructure, including the services of the European Union Customs Authority. Recital (3) then sets out a careful list of what enters the calculation and what does not, claiming „conservative assumptions”, an assessment considered „moderate” and „a reasonable and as realistic as possible projection” of the volume of goods imported in distance sales. No number accompanies those adjectives. There is no estimated administrative cost per item, no projected number of consignments, not even an order of magnitude for the revenue. Anyone wanting to find out whether 2 euro approximates a real cost or is a round figure chosen for simplicity has nothing in the act to check it against, and the Commission’s first report will cover the 2026-2028 period, so it will be ready after the fee has been collected for roughly two years.
The second observation comes from combining the dates rather than reading them one by one. The Union Customs Code applies, as a general rule, from 21 September 2027, while the handling fee applies from 1 November 2026. Between those two dates lie 324 days, roughly ten months and three weeks, during which a single piece of the European customs reform operates, namely the one that brings money to the customs authorities. The simplifications and the quid pro quo promised by the same Code come later: the customs warehouse for distance sales in Article 145 and the reduced amount tied to it, in Article 20(4), become applicable only from 1 July 2028, under Article 287(5)(a). Recital (79) of the Code justifies that reduced amount on the ground that it is „easier and more effective for the customs authorities to supervise bulk quantities of goods stored in a warehouse than goods packed in individual parcels and directly shipped to the consumer”, so the economic argument holds from day one, but the reduction does not.
The third observation concerns the relationship between the deadline imposed on the addressee and the one the administration grants itself. The economic operator has ten days from publication, from 22 October to 1 November 2026, to be in a position to calculate, declare and pay a fee on a new unit of measurement, the declared item rather than the parcel. The Commission has, under Article 20(7) of the Code, until 30 June 2028 to provide the Union-level IT solution for calculating the very same fee, which is 617 days from that same publication, more than sixty times as long. Throughout that stretch, 607 days from the date of application, the calculation is done on each operator’s own means. And the collection procedure is not even mandatory: the wording in Article 20(11), „may adopt”, leaves the choice to the European Commission, so the fee falls due before the procedural framework that ought to accompany it.
The fourth observation concerns the distributive effect, which the act mentions nowhere. A flat fee per item is regressive by construction: on an object worth 3 euro it means roughly 67% on top of the price, on one worth 20 euro 10%, on one worth 100 euro 2%. A typical basket from a platform outside the Union, with five different small products at 4 euro each, pays 10 euro on 20 euro of goods, half the value. If the declared aim is to cover supervision costs, the effect is coherent, since small and numerous objects cost the most to check. If the unstated aim is to discourage direct imports of cheap goods, then the instrument works, but in that case it ought to be said, and an act that rests its amount exclusively on costs cannot also invoke the trade protection effect.
What should be changed
- Publish the calculation, not just the result. The estimated administrative cost per item, the projected number of consignments and the contribution of each cost component should accompany the regulation, in an annex or in a working document cited in the preamble. Without them, the biennial review in Article 20(8) of the Code has no benchmark to measure against, and any future adjustment will look arbitrary.
- Correct the date of application or the wording of recital (4). A single clarification, saying plainly whether the obligation arises for declarations of 1 or of 2 November 2026, takes 1 November out of the zone where two customs authorities can decide differently.
- Set the reduced amount for the customs warehouse for distance sales now. Even if Article 20(4) of the Code becomes applicable on 1 July 2028, fixing the figure in advance would let operators decide whether applying for a warehouse authorisation is worth it, and that decision is taken two years ahead, not in the month the rule starts.
- Adopt the implementing act on the collection procedure before the date of application. Article 20(11) of the Code leaves it to the Commission’s discretion, and the result is that a fee due from 1 November 2026 is declared by analogy with customs debt. A procedure of its own, with the monthly deadline, the format of the records by item and the rules for corrections, would remove differences of practice between Member States.
- An express conversion rule for the States that do not use the euro. The amount is set in euro, and the regulation does not say at what rate and on what date it is converted into lei. The clarification changes no amount in euro, but it spares the customs authorities outside the euro area a choice nobody delegated to them.
- A ceiling per consignment, or a fee that tapers with multiple positions. Charging per item closes the bundling route, but it turns any order with many small products into a disproportionate cost. A ceiling per consignment, calibrated on the real cost of checking one parcel, would keep the anti-avoidance effect and take out of the formula the outcomes in which the fee reaches half the value of the goods.
Original text of the legal act
The text below is reproduced in Romanian, the official form of publication.
The full text, as published in the Official Gazette of Romania
Official Journal of the European Union, L series, 2026/2152 of 22 October 2026 2 pages PDF, 453 KB
Open the official PDFDownload the PDF
The viewer is not shown on small screens. Use the buttons above to open or download the file.
This article is for informational purposes only and does not constitute legal advice. For specific situations, consult a licensed attorney or tax advisor.