
In brief
- Joint Order No. 1,613/956/2026, signed by the Romanian Customs Authority and ANAF, sets out exactly what “occasional” transport of excisable goods (tobacco, alcohol) brought from another EU state by an individual for personal use means, so it is not confused with undeclared economic activity.
- An electronic register is set up at the Customs Authority, recording customs staff findings on a standardised “findings sheet,” signed by the officer and the person checked.
- The occasional character is lost if the same person’s repeated shipments exceed the quantity ceilings set in the Tax Code, calculated over 40 days and over one year from the last recorded finding.
Published: Official Gazette of Romania (Monitorul Oficial) No. 652 of 6 August 2026
In force from: 6 August 2026
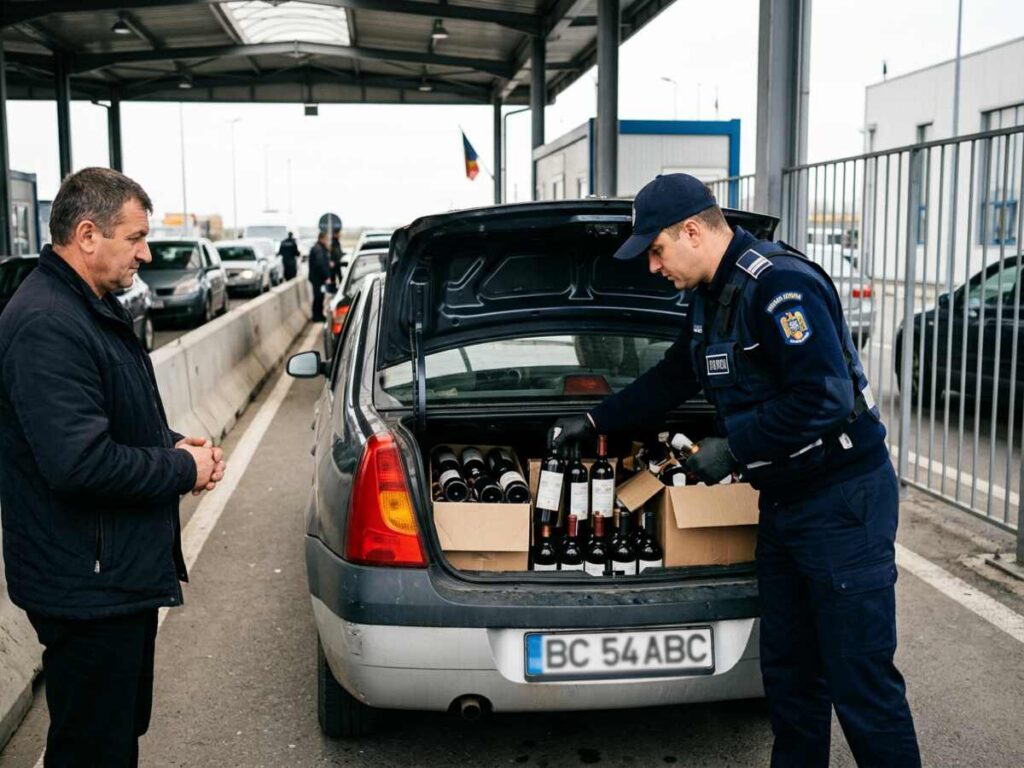
If you bring a few bottles of wine or a carton of cigarettes into Romania bought in Hungary or Bulgaria, you have nothing to declare. If you do this repeatedly, right at the limit of the allowed quantities, you risk being treated as a trader dodging excise duty. Joint Order of the President of the Romanian Customs Authority and the President of ANAF No. 1,613/956/2026, published in Official Gazette of Romania No. 652 of 6 August 2026, sets out the exact criteria control bodies use to tell the two situations apart.
Under the order, transport is considered occasional if it cumulatively meets three conditions: it is carried out exclusively for personal, non-commercial purposes; it is not part of a successive series of shipments by the same person, of a kind indicating economic activity; and the total quantity carried does not exceed, within 40 days of the last recorded finding, the ceilings set in Article 413(3)(a) and Article 4483(5) of the Tax Code, nor, within one year, the ceiling in Article 413(3)(b).
To be able to track these shipments over time, the order sets up, at the Romanian Customs Authority, the Electronic Register for recording individuals’ occasional imports of excisable goods, fed by findings from customs and ANAF staff, recorded on a standard findings sheet (annexed to the order).
What it changes in practice
Individuals who occasionally bring excisable goods from another EU state now have a clear, written benchmark for what “occasional” means, instead of depending on the on-the-spot judgment of the customs officer at the border.
Every finding at the border (or during an inland check) is recorded on a standard sheet, with the holder’s details, the goods’ origin, the vehicle’s registration number, and the exact quantities by category of tobacco and alcohol products (cigarettes, cigars, smoking tobacco, spirits, intermediate products, still wine, sparkling wine, beer).
The sheet is signed by the finding officer and by the person checked; if the person refuses to sign, the finding is still recorded, with a note of the refusal. The person checked may request, in writing, an electronic copy of the sheet, to be sent within a maximum of 7 days to the email address given.
The electronic register allows successive findings for the same person to be linked, essential for checking the two time-based ceilings (40 days and one year), which determine whether the transport remains “occasional” or becomes suspected undeclared economic activity.
What has changed compared with the previous situation
The Tax Code (Law No. 227/2015) already set out, in Articles 413 and 4483, the quantity ceilings and the concept of occasional transport for excisable goods brought by individuals from another EU member state, but without an operational definition applicable uniformly by control staff. Order No. 1,613/956/2026 completes this framework with the exact cumulative criteria and the institutional record-keeping mechanism (the electronic register and the findings sheet), missing until now.
The key novelty is the introduction of a tool for monitoring over time: until now, an isolated finding at the border could not be automatically linked to the same person’s earlier findings; the electronic register solves exactly this gap.
Advantages and disadvantages
What it improves
- Gives ordinary travellers predictability: as long as quantities and frequency stay under the ceilings, transport is clearly occasional, without the risk of arbitrary interpretation.
- Standardises the finding procedure nationwide, through the single sheet, used equally by the Customs Authority and by ANAF.
- Enables genuine detection of illegal trade in excisable goods disguised as repeated “personal” shipments, by linking findings in the electronic register.
- Gives the person checked the right to an electronic copy of the sheet, so a written record of the interaction with the authorities.
What remains a problem
- The order itself does not publish the exact values of the quantity ceilings; these must be looked up separately in the Tax Code, which complicates verification for an ordinary citizen.
- Refusing to sign the findings sheet does not stop the recording, which may be perceived as pressure on the person checked, even though the procedure is meant to protect the accuracy of the record.
- The electronic register involves collecting and keeping personal data (identity, address, citizenship, repeated movements), without the order detailing retention or access rules for this data.
- It does not explicitly state what happens, procedurally, to a shipment exceeding the ceilings: whether excise duty applies retroactively, fines, or other sanctions, referring back to the Tax Code’s general provisions.
Practical advice
- If you frequently buy alcohol or tobacco in another EU state, keep your own record of quantities and dates, so you can be certain you stay within the 40-day and one-year ceilings set by the Tax Code.
- At a customs check, always ask for a copy of the findings sheet, in writing, when it is filled in; you have a legal right to an electronic copy within 7 days.
- Never sign a findings sheet you disagree with without noting your objections; a refusal to sign is recorded separately and does not affect your right to challenge the finding later.
- If you frequently carry quantities close to the ceiling, factor in the risk that authorities may read the shipments as a “successive series” suggesting economic activity, even if each individual shipment respects the ceiling.
Frequently asked questions
What does “occasional character” of transporting excisable goods mean?
What products does this order cover?
What happens during a customs finding?
Can I get a copy of the findings sheet?
What happens if my shipments exceed the legal ceilings?
Original text of the legal act
The full text, as published in the Official Gazette of Romania
Official Gazette of Romania no. 652 of 6 August 2026 16 pages PDF, 105 KB the act starts on page 14
Open the official PDFDownload the PDF
The viewer is not shown on small screens. Use the buttons above to open or download the file.
This article is for informational purposes only and does not constitute legal advice. For specific situations, consult a licensed attorney or tax advisor.